Verified Firm Faces Silent Suspension by Payment Platform
A digital marketing company provided all required legal and financial documents to Square, yet the account was frozen without explanation after a delayed appeal.
By Justin Brooks ·
Small businesses that operate entirely online often depend on payment processors to keep their cash flow moving. For a marketing and SEO firm based in the local area, this dependency became a source of significant frustration when its account with Square was suspended. The company had completed every step required for verification. It provided government issued identification for its owners. It linked a valid business bank account. It submitted the Employer Identification Number document directly from the Internal Revenue Service. It connected the bank account to the Square platform using third party software. It produced the formation documents for its limited liability company. It also held a valid contract with a client for the full amount of money in dispute.
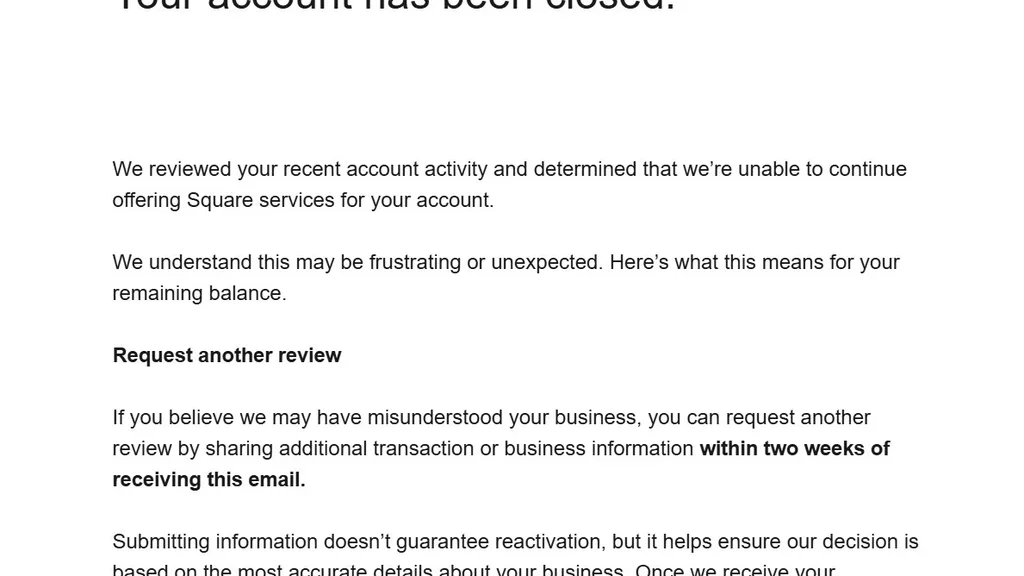
Despite this thorough preparation, Square suspended the account. The suspension was not due to a missing document. The bank account had not failed verification. The IRS had not flagged the tax ID as invalid. Instead, the platform cited a rule that the business did not break. In fact, the rule was not even listed as a standard reason for suspension in the company's guidelines. The automated system had made a decision, and it did not appear to accept questions. The business owner described the situation as a machine doubling down on a non existent rule, leaving the firm with no clear path to resolution.
The firm filed an appeal to reverse the decision. Square promised a response within ten days. The company waited for two weeks. When the response finally arrived, it was a denial. There was no explanation for the suspension. There was no reasoning for the denial. There was no human being to call, no office to visit, and no face to look at while the company explained why its money and business were no longer welcome. The decision came solely from an automated system.
This outcome highlights a specific tension in the terms of service that Square presents to its users. The General Terms of Service, specifically Section 12, state that the company may terminate the terms or suspend or terminate the account at any time for any reason. The phrase at any time for any reason implies that a specific cause is optional. The company can act without providing a detailed justification. Section 13, which covers the effect of termination, adds that the company will not be liable to the user or any third party for compensation, reimbursement, or damages resulting from the termination or suspension of services. This clause allows the platform to hold funds and restrict access without financial liability for the disruption.
The Payment Terms contain similar provisions. Section 12 of these terms allows Square to defer payout or restrict access to proceeds, either temporarily or indefinitely. This means that revenue already earned by a business, such as a client payment that has already been made, can sit in a company account while the platform decides the fate of the merchant. Section 14, regarding the reserve for holding funds, states that the company may require a reserve for any reason related to the use of services. The amount of this reserve is reasonably determined by the company itself. It is not set by a bank, a regulator, or a judge. It is determined by the payment processor.
Perhaps the most striking detail in the contract is found in Section 1 of the Payment Terms. It opens with the statement that Square is not a bank. The company identifies itself as a payment facilitator and a processing platform. It acts as the pipe that moves money, not the reservoir that holds it. Yet, this software company holds more power over a small business than the traditional bank that actually houses the funds. Traditional banks must follow established rules, explain their decisions, and answer to regulators. Square operates with a suspension button that appears to have no off switch.
When a business attempts to challenge these decisions, the contract structure presents significant hurdles. Section 22 of the General Terms prohibits class actions and juries. Disputes must go through individual arbitration in Oakland, California. Section 19 caps the total liability of the company at the fees it earned from the user in the three months prior to the issue, or five hundred dollars, whichever is greater. This cap suggests that the maximum value of the business relationship, according to the contract, is five hundred dollars. Section 7 further states that if there is a dispute about account ownership, Square will be the sole arbiter of that dispute in its sole discretion, and its decision will be final and binding on all parties.
The company also maintains a list of unsupported industries in its Payment Terms. Item six on this list includes direct marketing or subscription offers or services. A marketing and SEO firm exists close to this category. The automated system may not need the rule to be strictly accurate. It only needs the rule to be convenient for the algorithm. The machine scrutinizes the business with zero reason and zero explanation. The merchant, who verified every step, is suspended by a rule that may not even be a valid reason for suspension. The appeal process, which took twice as long as promised, ended without a word.
The business cannot easily dispute this outcome. To dispute it is to enter into arbitration in the company's chosen city, under its chosen rules, for a prize capped at a modest amount. The contrast with traditional banking is sharp. A bank must explain itself. A regulator must show its work. A human being must look a client in the eye and provide a reason. In the case of the suspended Square account, there is no one. There is a dashboard. There is a denial. There is a machine that has never met the business, never read the client contract, and never spoken to the customer.
This scenario illustrates a broader shift in how digital commerce operates. A company that is not a bank is acting like one. An automation system is making high stake decisions with little transparency. A merchant who did everything right is caught in a system that offers little recourse. The verified business did not need to do everything right, according to the terms of service. The platform did not need the business to be perfect. It only needed the authority to suspend the account.
Until companies that are not banks start acting like they are, every small business in the country is one algorithm away from losing its money, its account, and its voice. The process offers no reason and demands no explanation. The merchant is left with a frozen account and a contract that limits its rights. The system relies on the assumption that small businesses will accept the terms rather than fight the odds. The result is a landscape where verification is a formality, and suspension is a tool that requires no justification. The firm in question had provided its ID, its tax documents, its bank details, and its client contract. It received a suspension and a denial. The machine had made its decision, and it did not take questions.
More Business · Unethical Practices · Report a business · Got a Story?